Authors
Article Highlights
- Typical rents in Minneapolis have been stable, with recent uptick
- New multifamily construction in Minneapolis has stalled
- Headwinds against new housing are stronger than impact of reforms
In 2019, the City of Minneapolis adopted its Minneapolis 2040 Plan. With a mix of policy changes to encourage more housing affordability, this comprehensive plan is based on an expectation that building more housing would constrain rent growth. Seven years in, what’s happening in Minneapolis?
Answering that question is complicated because impacts of the 2040 Plan are hard to isolate from the ups and downs of real estate investment. New analysis and engagement from our team provide some insights. Findings from data updates to our Minneapolis Housing Indicators dashboard show that compared to a grouping of similar cities from across the country, Minneapolis has indeed seen lower rent growth.
At the same time, new multifamily development in Minneapolis has also slowed more than in our national comparison group. Feedback from some market players suggests that slow rent growth, accompanied by national and local headwinds against new construction, may be chilling further new housing development in Minneapolis. Unless there are substantial decreases in construction, operating, and borrowing expenses, rents in Minneapolis will remain too low for new development to be financially viable without additional support. Let’s dig into what we’re seeing.
Rents in Minneapolis have begun to edge upward
For a data-based understanding of trends in Minneapolis, we analyzed 2025–2026 updates to our dashboard. According to new data from Apartment List, rents in Minneapolis remain below those in our comparison cities.1 The median rent paid for new leases in our dashboard’s comparison group, weighted and adjusted to match Minneapolis’ median rent in December 2019, was consistently more than $200 a month higher than Minneapolis’ median rent from June 2022 through the end of 2025.
Since 2025, however, the difference between the median rent in Minneapolis and our comparison group has narrowed to $150, according to the most recent data. The narrowing is a result of rents in Minneapolis ticking up at a faster rate relative to our comparison group: from January 2025 through August 2026, Minneapolis’ median rent increased 8.9 percent while our comparison group’s median rent increased only 1.8 percent.
From 2022 through early 2025 the median rents paid for new leases in Minneapolis were stable, albeit with seasonal variations. In August 2026 (the most recent estimate as of this writing), the median rent was $1,469, up 3 percent year-over-year and a new high. According to CoStar, another data provider, quarterly average rent in Minneapolis reached a new high of $1,528 in June 2026, up 2.2 percent over June 2025.
Multifamily permitting has stalled in Minneapolis
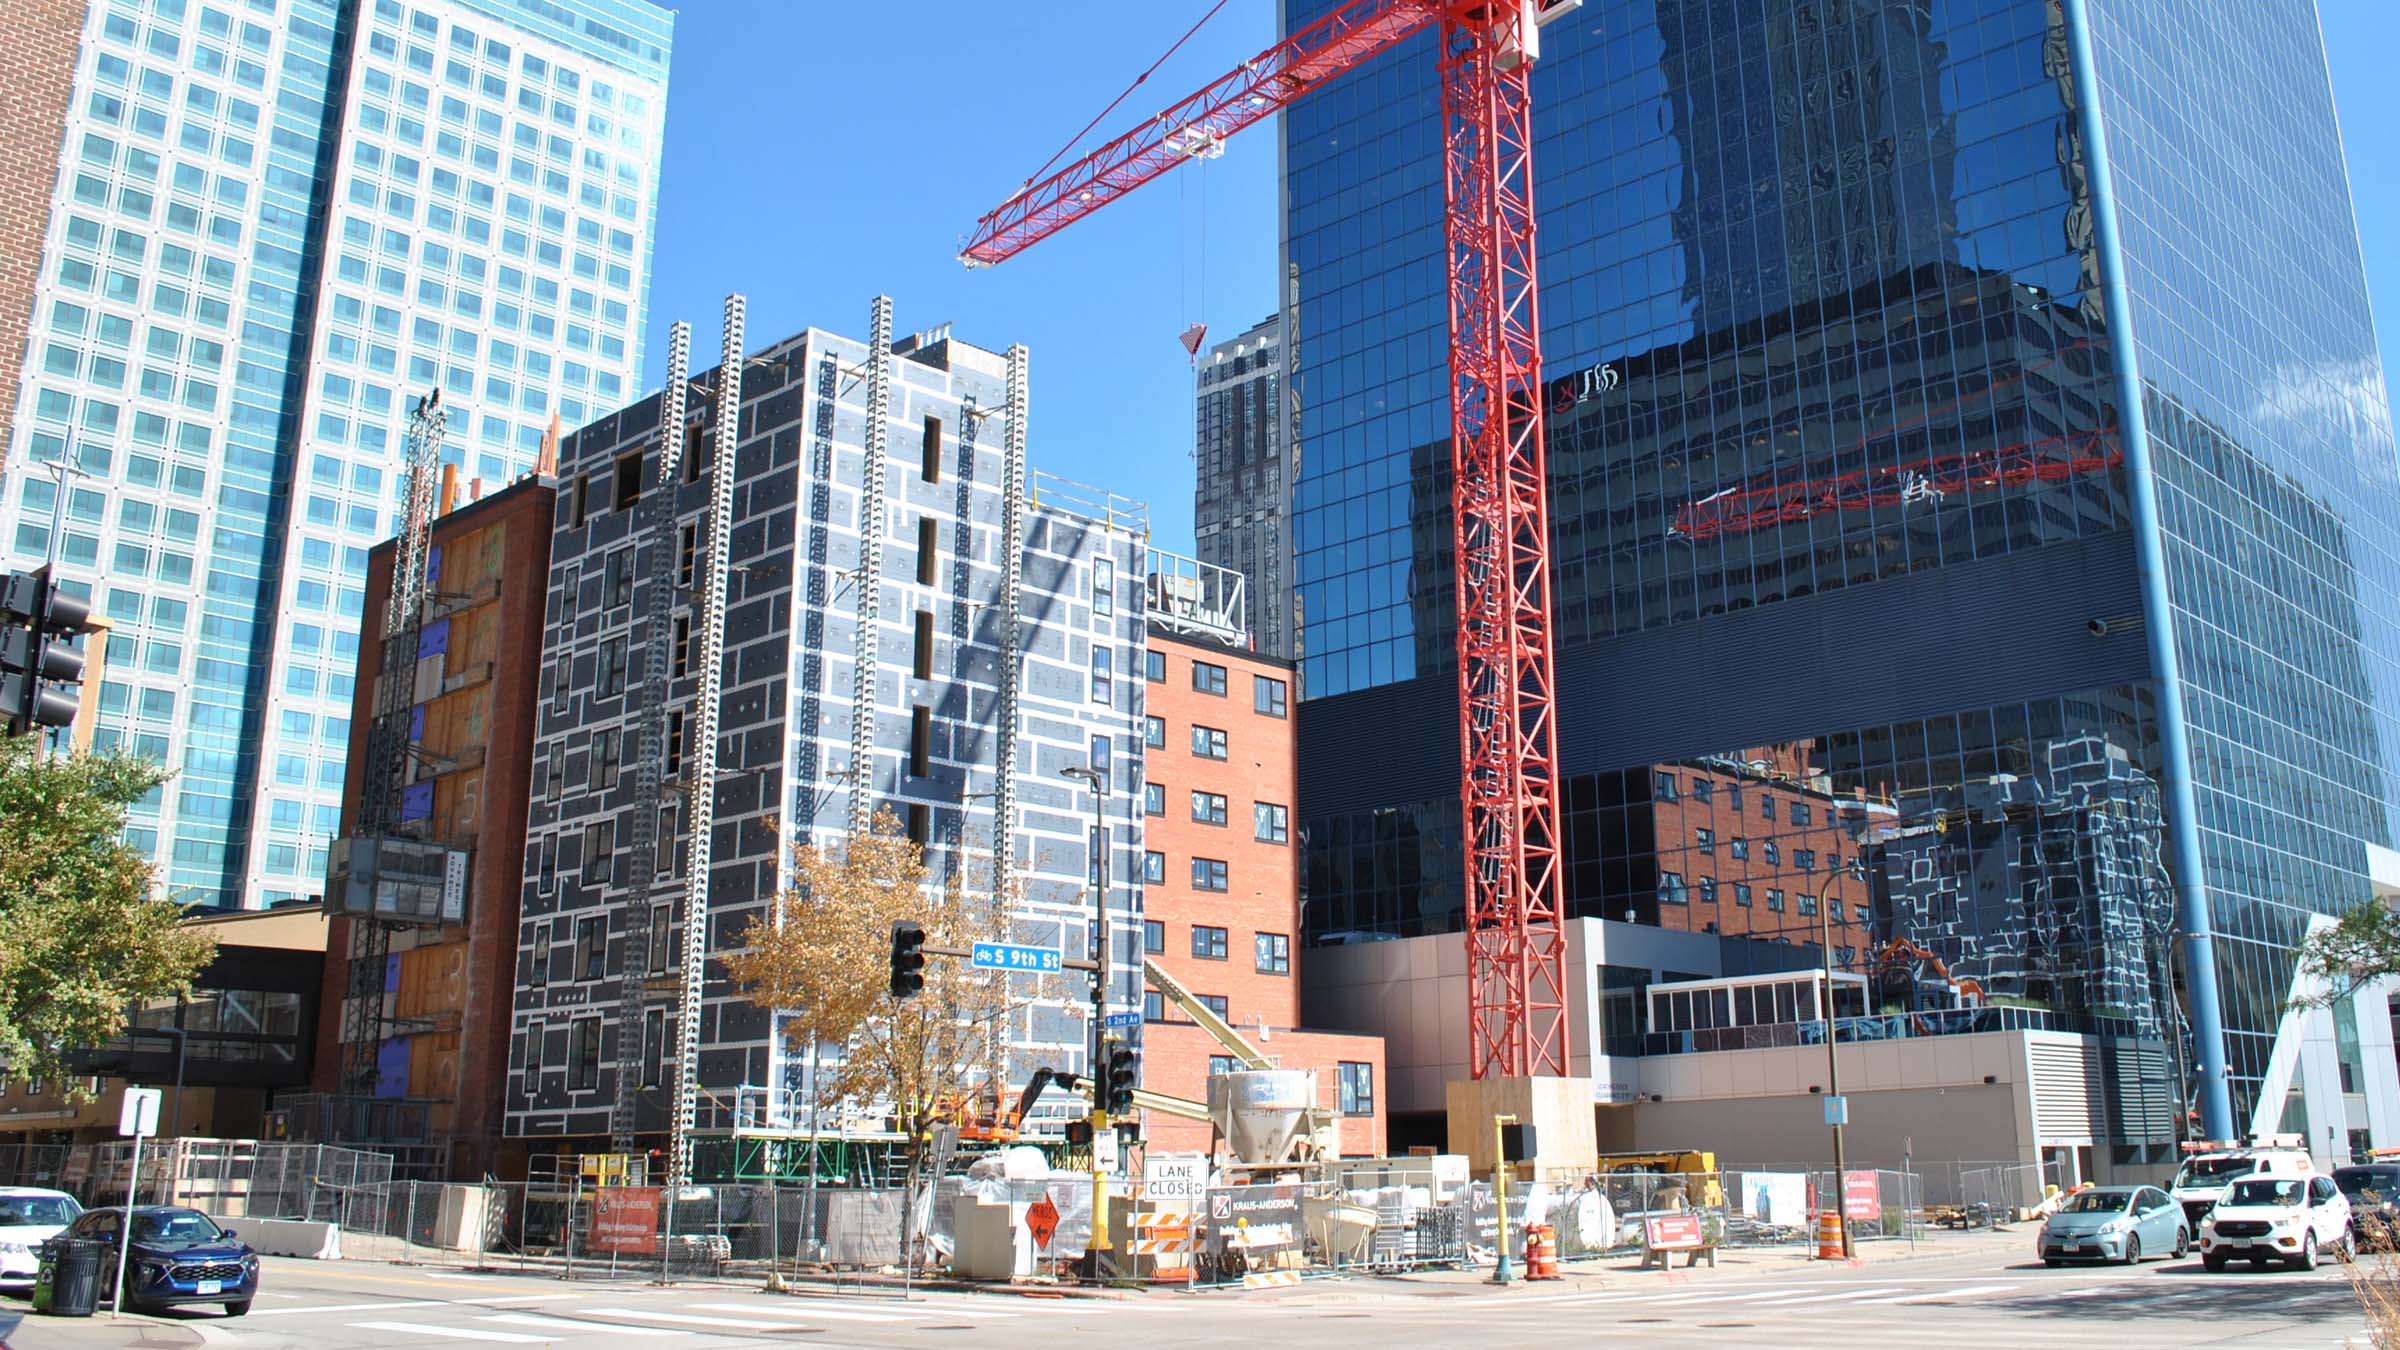
New multifamily development in Minneapolis has slowed more than in our national comparison group. Minneapolis saw a 91.6 percent drop in multifamily permitting from a recent peak in 2022 to a trough in 2025. Our comparison group saw a 64.3 percent drop in permitting from a recent high point in 2021 to a low point in 2024, followed by a small increase in 2025. Weighted to Minneapolis’ pre-2019 levels, the national comparison group’s 2021 permitting peak was 17 percent higher than Minneapolis’ 2022 peak. Multifamily permitting in the comparison group in 2025 was five times higher than in Minneapolis.
For context, from 2018 through 2022, Minneapolis permitted more multifamily housing than in any previous five-year period in recent history, adding more than 18,000 new units in multifamily buildings (defined as those with five or more units). The number of new multifamily units permitted peaked at 4,646 in 2019. The city permitted more than 3,000 multifamily units per year in 2018, 2020, 2021, and 2022.
Since then, permitting of new multifamily housing in Minneapolis has fallen off dramatically. The city saw 1,043 new multifamily units permitted in 2023 and only 351 and 300 new units permitted in 2024 and 2025, respectively. In other words, in each of the years 2024 and 2025, Minneapolis permitted the equivalent of less than 10 percent of the new units permitted in 2022. The last time Minneapolis permitted 300 or fewer new multifamily housing units in a year was in 2008, the bottom of the Great Recession.
The 2040 Plan allows duplexes and triplexes in areas previously zoned for only single-family housing. From 2020 through 2025, Minneapolis permitted 317 new units in duplexes, triplexes, and fourplexes, 2.4 more units over the six-year period than our comparison group (scaled to Minneapolis). Though these new units might not have been built (or would have been built in different locations) but for the 2040 Plan, they are equivalent to just 2 percent of the 12,335 units permitted in multifamily buildings during the same years. Of the 106 new duplex, triplex, and fourplex buildings containing these 317 units, 47 are on parcels that previously allowed only single-family homes.2
2040 Plan clarifies what’s expected of housing developers
While our dashboard provides both local data and comparative national data, we sought additional nuance behind the numbers. For an on-the-ground perspective of what’s happening in Minneapolis, we interviewed an array of multifamily developers, owners, and investors over the summer of 2026.
Through its 2040 Plan, the City of Minneapolis aspired to reduce the costs of new development by allowing more types of housing in more places and increasing the predictability of land use approvals. Time is money for developers: one developer told us that for larger apartment buildings, every extra month spent getting land use approvals can add upwards of $100,000 in cost.
The developers we interviewed praised some of the 2040 Plan’s aspects. One developer told us, “The 2040 Plan makes Minneapolis one of the most developer-friendly cities in the country. Per the letter of the law, this is what I can build. If I build within the specifications of the plan, the odds of getting my project into construction are high. The plan lets me know where not to waste my time. This is the beauty of this plan—it makes the rules for development very clear.”
Developers remain skeptical about building in Minneapolis
In many places across the country, new multifamily housing faces an array of headwinds that make it harder for projects to achieve feasibility—or, as developers say, to “pencil out.” High borrowing, operating, and construction costs and low rent growth have challenged the profitability of multifamily apartments and slowed multifamily construction in many markets, both nationally and locally. When rents fall below costs, developers “can’t build, because on the day they open, their projects are worth less than they cost to build,” as one interviewee said.
One developer we interviewed observed that “construction costs have skyrocketed. A project we built in 2023 would cost 30 percent more to build today. The cost of debt is more expensive. On the operating end, everything is out of our control. We can control staff costs, but we can’t control taxes or insurance, and those have gone up considerably.”
Minneapolis itself faces additional headwinds, some stemming from other housing policies the city adopted both before and after the 2040 Plan. One developer described Minneapolis as “a challenging place to build from a cost, tenant, and operations perspective. It’s one of the hardest places to operate because of regulatory requirements, however well-intentioned they may be.” Developers called out Minneapolis-specific policy provisions—the city’s inclusionary zoning policy, requirements for first-floor retail, expanded protections that make evicting problem renters more difficult, height minimums that block development of less costly building types, and so on—as collectively making it “extraordinarily hard to get projects to pencil without additional financing.” While we have not inventoried what similar policies exist in our comparison cities, these policies influence the calculus of costs and revenues for new development in Minneapolis.
Consider the city’s inclusionary zoning policy, which requires developers of market-rate apartments to include rent- and income-restricted units. For example, rent and utilities for a two-bedroom unit affordable to a household earning 60 percent of the area median income must be no more than $1,776 per month. One developer told us such rents support construction costs of $150,000–$175,000 per unit. With today’s per-unit construction costs more like $325,000, inclusionary zoning creates a gap of at least $150,000 per affordable unit. If a 100-unit building requires 8 percent of units to be income-restricted, that becomes a funding gap of over $1 million. As the developer noted, “That is a big tax on new housing.”
Similarly, developers perceive requirements to build first-floor retail as a tax on new housing development because “the economics don’t make sense to fill it.” Each specific policy that adds cost is unlikely on its own to tip the scales on the feasibility of housing construction. Indeed, research commissioned by the city “did not suggest that the [inclusionary zoning] policy stands in the way of new building.” However, these additional costs cumulatively make new development more challenging.
Developers interested in owning rental property in Minneapolis can acquire existing apartment buildings at lower upfront cost than building new. Recent sales data indicate that apartment building towers, typically steel-framed, are selling in the neighborhood of $300,000 per unit while replacement costs are more like $400,000–$500,000 per unit. Wood-framed apartment buildings, typically five to seven stories, are selling for $250,000 per unit while replacement costs are closer to $300,000 per unit. As some areas in Minneapolis have height minimums that require steel framing, these cost variations across construction types also make height minimums impossible to meet.
Perceptions of political instability or uncertainty have scared away some national investment in multifamily development in Minneapolis. For example, discussion of rent stabilization in Minneapolis “dampened investor sentiment,” one developer told us. Investors and lenders who are worried about prolonged eviction timelines and renter protections may require larger cash reserves, forcing developers to raise more equity or delay construction. Other investors have claimed that they “won’t invest in Minneapolis.”
Weak demand in Minneapolis remains a challenge for developers as new development chases fewer residents. Population growth in Minneapolis has slowed. In the half-decade since 2020, Minneapolis has added roughly 5,000 residents, compared to over 47,000 over the previous decade (2010 to 2020). One owner of multifamily housing told us, “In summer 2020, many of my renters left Minneapolis due to concerns about crime and mostly moved to first-ring suburbs, such as St. Louis Park or Richfield. They have yet to return to the city.”
Slow rent growth may now be hindering continued housing investment
The slow rent growth in Minneapolis has increased the city’s affordability for renters. The 2026 rent limit for one-bedroom apartments affordable to households earning 60 percent of the area median income is $1,479, which is $153 above Apartment List’s reported median one-bedroom rent of $1,326 for Minneapolis in August 2026. By definition, half of all rent charged in the city is below this median rent. In other words, more than half of one-bedroom apartments in Minneapolis charge rent below the limit for income-restricted affordable housing for low-income households. Even so, more than four in 10 renting households in Minneapolis are already paying more than 30 percent of their income in housing costs.
Against the increasing expenses of operating multifamily housing, inflation-adjusted rents have fallen. Adjusted to January 2026 dollars, overall rents in Minneapolis have fallen nearly 20 percent, dropping from $1,777 in January 2020 to $1,436 in August 2026. Over the same period, inflation-adjusted rents in our national comparison group dropped just over 10 percent. “In a healthy market, rents go up, tracking inflation,” said one of our interviewees. “The hard part over the last three to five years is that rents haven’t gone anywhere, but our expenses have increased 5 to 7 to 10 percent a year.” When asked about rent trends, one developer observed, “Rents haven’t moved in five years. They’re beginning to move a little bit now because we haven’t seen a lot built.”
The developers we interviewed consistently said that they “need to see more sustained and larger positive signs of rent growth” before they will consider development in Minneapolis. One commented, “While it’s convenient to say that rents are going up, they haven’t caught up with the rise in construction costs over the last six to seven years. This is why we don’t see the development.” Another said developers are “trying to solve for how much income a building will generate versus the cost of building, owning, and maintaining it. No one will do that for a zero percent return. You can buy a Treasury bill for less risk.”
Looking ahead
Will the 2040 Plan’s impact on the cost of building new housing allow new construction in the city to pencil out at lower rents than elsewhere? Only time will tell. The Federal Reserve Bank of Minneapolis will continue to update its Minneapolis Housing Indicators dashboard through the city’s adoption of its 2050 Plan later this decade. This work supports housing policy that advances the economic well-being of low- and moderate-income residents and reflects the Minneapolis Fed’s mission to pursue an economy that works for all of us. We look forward to the insights that future years of data will reveal.
Appendix: Our dashboard gets a refresh
As noted above, our analysis draws on our updates to the Minneapolis Housing Indicators dashboard, which we launched in 2020–2021 to track shifts in housing supply and affordability following the 2019 adoption of the Minneapolis 2040 Plan. Our dashboard reports on 11 core indicators and monitors an additional 29.
Every three years, the Minneapolis Fed thoroughly reviews the dashboard to ensure that we’re using the best possible data sources and clearest indicators. This year’s refresh incorporates two new core indicators, multiple revisions to better match the existing indicators to the 2040 Plan’s goals, an updated approach to measuring statistical significance, and additional functionality for dashboard users. Core updates include:
- Adding a comparison group to our indicator of new permitted units in duplex, triplex, and fourplex housing.
- Introducing a new indicator for vacancy rates, with a comparison group.
- Measuring statistical significance for housing composition, housing cost burden, and rental vacancy rates based on the most recent data alone.
- Creating a side-by-side view of core indicators, allowing for a comprehensive understanding of how related measures interact.
- Adding the option to adjust the dashboard’s “Price of Housing” indicators for inflation.
We redefined our measure of housing composition to focus on the share of single-family detached homes in the housing stock. A declining share of single-family detached homes indicates other housing types are making up a larger portion of the city’s housing stock. Single-family homes declined from 40.7 percent of the housing stock in 2019 to 39.9 percent in 2024.
Endnotes
1 In previous iterations of our dashboard, we used median rent from the U.S. Census Bureau’s American Community Survey (ACS), which samples from a larger portion of renting households across the city, including those renting single-family homes. In this new iteration, we use rent data from Apartment List and CoStar, two private companies that track the rental market. While the ACS reflects the experiences of longer-term renters, these private data sources rely heavily on recent rental listings, which may provide a more accurate picture of current rental market conditions.
2 These numbers use building permits data from the Metropolitan Council which differ from the Census Bureau Building Permits Survey numbers.
Libby Starling is Senior Community Development Advisor in Community Development and Engagement at the Federal Reserve Bank of Minneapolis. She focuses on deepening the Bank’s understanding of housing affordability, concentrating on effective housing policies and practices that make a difference for low- and moderate-income families in the Ninth Federal Reserve District.
Maxine Xu is a data scientist in the Minneapolis Fed’s Community Development and Engagement division, where she develops data tools and leads analyses to explore issues affecting the economic well-being of low- to moderate-income communities.